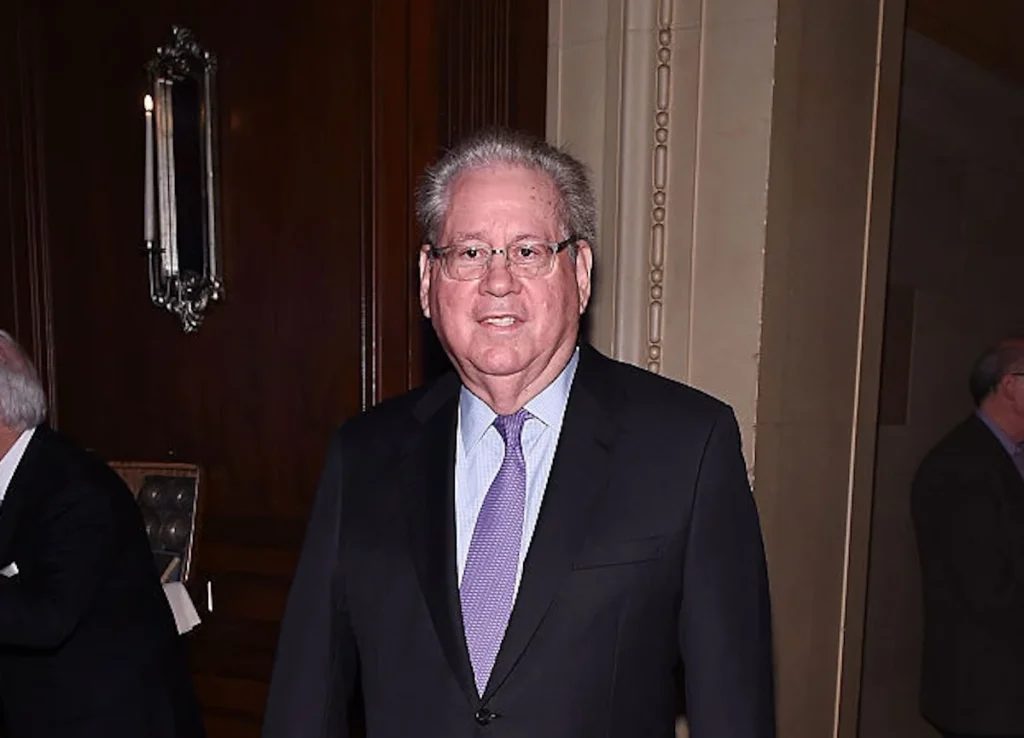
The intersection of high finance and the upper echelons of the art world has always been a space of immense wealth and strategic maneuvering. However, the recent announcement that Sotheby’s will auction a significant portion of George Allen Weiss’s private art collection marks a somber turning point for one of Wall Street’s veteran figures. Weiss, the founder of the now-bankrupt Weiss Multi-Strategy Advisers, is turning to the auction block to resolve a mounting mountain of debt that spans from major financial institutions to the Internal Revenue Service (IRS).
This liquidation, scheduled for Sotheby’s marquee November sales, represents more than just a change of ownership for masterpieces by the likes of Francis Bacon and Pablo Picasso; it is a clinical exercise in debt satisfaction. As the hammer falls in New York this autumn, the proceeds will be funneled directly toward a $123 million debt owed to Bank of America—a loan that was uniquely secured by the very canvases hanging on Weiss’s walls.
Main Facts: The Sotheby’s Consignment and the Debt Burden
The core of the upcoming auction involves 16 works from Weiss’s personal holdings. According to statements made by Weiss’s attorney, Paul Battista, during a recent court hearing, these works will be featured prominently in Sotheby’s prestigious November evening and day sales. These "marquee" events are the centerpiece of the global auction calendar, typically attracting the world’s most affluent sovereign wealth funds, private equity moguls, and institutional collectors.
The financial stakes are staggering. Court documents reveal that Weiss’s liabilities are not limited to a single lender. As of 2025, his bankruptcy filings indicate a complex web of debt:
- $180 million owed to the Internal Revenue Service (IRS).
- $121.4 million owed to Bank of America (secured by the art collection).
- $113.5 million owed to Jefferies Strategic Investments.
To mitigate the risk of a market downturn affecting the repayment, Sotheby’s has reportedly provided a "minimum price guarantee" for six of the 16 works. A guarantee in the auction world acts as a form of insurance for the seller; the auction house (or a third-party partner) agrees to purchase the work at a pre-determined price if the bidding fails to reach that threshold. This ensures that a baseline of capital will be generated to begin chipping away at the Bank of America debt.
The collection itself is a "who’s who" of 20th-century art history. The holdings include works by:
- Francis Bacon: Known for his visceral, emotionally charged figurative paintings.
- Pablo Picasso: The titan of Modernism whose works remain the gold standard for collateralized loans.
- Paul Cézanne: The Post-Impressionist master often cited as the bridge between 19th-century Impressionism and 20th-century Cubism.
- Andy Warhol: The king of Pop Art, whose market liquidity makes his work ideal for rapid debt recovery.
While 16 works are headed to Sotheby’s, reports suggest that Weiss’s total collection includes at least 25 additional pieces, which may be sold in subsequent tranches or through private treaties depending on the success of the November auctions.
Chronology: From Asset Management to Asset Liquidation
The downfall of Weiss Multi-Strategy Advisers and the subsequent liquidation of George Weiss’s art collection is a saga that spans decades, beginning with the optimism of the late 1970s and ending in the cold reality of Chapter 11 bankruptcy.
1978–2022: The Rise of an Empire
George Allen Weiss founded Weiss Multi-Strategy Advisers in 1978. Over the next four decades, the firm grew into a significant player in the hedge fund space. Weiss, a graduate of the Wharton School at the University of Pennsylvania, became known not only for his financial acumen but also for his philanthropy and his "Horatio Alger" success story. By the time he received an award from the Horatio Alger Association in 2022, his firm was managing an estimated $2.7 billion in assets. During these years of prosperity, Weiss meticulously built an art collection that functioned as both a personal passion and a sophisticated asset class.
2023: The First Signs of Distress
The tide began to turn in early 2023. Facing mounting financial pressures and a changing landscape for multi-strategy hedge funds, the firm began to struggle with liquidity. In an effort to stave off a full collapse, Weiss sought to sell one of his crown jewels: a Claude Monet Nymphéas (1914–17). The painting was offered with an asking price of $36.5 million, specifically intended to pay down the debt to Bank of America. This move signaled to the market that Weiss’s art was no longer just a collection, but a lifeline.
2024: Bankruptcy and Tactical Sales
The firm officially filed for Chapter 11 bankruptcy protection last year. Following the filing, the liquidation process accelerated. In June 2024, reports surfaced that Weiss was preparing to sell a 1972 self-portrait by Francis Bacon through Gagosian Gallery, the world’s most powerful commercial art dealership. This followed earlier agreements to consign works by Picasso and the Neo-Impressionist Paul Signac. Despite these efforts, the scale of the debt necessitated a larger, more public exit strategy, leading to the current agreement with Sotheby’s.
November 2024 (Upcoming): The Marquee Sales
The 16 works are set to be the "main event" of the bankruptcy recovery process. The transition from private sales (via Gagosian) to a public auction (via Sotheby’s) suggests a need for the transparency and competitive bidding environment that only a major auction house can provide during a court-supervised liquidation.
Supporting Data: The Mechanics of Art as Collateral
The Weiss case provides a rare glimpse into the data-driven world of "art lending." For high-net-worth individuals, art is often an underutilized asset. Banks like Bank of America, Citibank, and JPMorgan Chase have robust art-lending departments that allow collectors to borrow against their holdings—typically up to 50% of the collection’s appraised value.
In Weiss’s case, the $123 million debt to Bank of America was directly secured by his artwork. This means the bank holds a "perfected security interest" in the paintings. If the borrower defaults or enters bankruptcy, the bank has the primary claim to the proceeds from the sale of those specific assets.
The involvement of Jefferies Strategic Investments adds another layer of complexity. According to Bloomberg, once the Bank of America loan is satisfied, any remaining proceeds from the Sotheby’s sales could be diverted to Jefferies and other junior creditors. However, given the $180 million owed to the IRS, the "waterfall" of payments—the order in which creditors get paid—will be a point of intense legal scrutiny in the bankruptcy court.
The use of guarantees for six of the works is a strategic move by Sotheby’s to secure the consignment. In a volatile market, a guarantee provides the bankruptcy estate with a "floor." If the works sell for significantly more than the guarantee, the estate (and thus the creditors) benefits from the upside. If they fail to attract bids, the auction house takes ownership, and the creditors still receive the guaranteed amount.
Official Responses: A Controlled Silence
As is common in high-profile bankruptcy cases involving sensitive financial negotiations, official commentary has been sparse.
- Paul Battista (Attorney for George Weiss): While Battista confirmed the details of the Sotheby’s agreement during a court hearing on Wednesday, he did not immediately respond to further requests for comment from ARTnews. His primary focus remains the court-approved liquidation plan to satisfy the diverse pool of creditors.
- Sotheby’s: The auction house has officially declined to comment on the specifics of the consignment, the identity of the guarantor, or the estimated values of the individual works. Sotheby’s generally maintains a policy of confidentiality regarding "distressed" consignments to avoid stigmatizing the artworks, which could potentially lower their perceived value at auction.
- Bank of America: The bank has remained silent, relying on court filings to assert its position as a secured creditor.
Implications: The Art Market as a Financial Barometer
The liquidation of the Weiss collection has broader implications for both the financial sector and the global art market.
1. The Vulnerability of Art-Backed Loans
The Weiss case serves as a cautionary tale for the burgeoning art-lending industry. While blue-chip art is often seen as a stable store of value, its liquidity is not instantaneous. The fact that it has taken over a year of legal maneuvering and multiple attempted sales to reach this point highlights the "friction" involved in liquidating high-value aesthetic assets compared to stocks or bonds.
2. Market Sentiment and "Distressed" Assets
When a large volume of high-quality work from a single, well-known collector hits the market due to financial duress, it can create a "buyer’s market" mentality. Savvy collectors may wait to see if they can acquire masterpieces at the lower end of the estimate range. Conversely, the "provenance" of a major hedge fund collection can sometimes add a layer of prestige that drives prices up. The November results will be a key indicator of whether the market views these works as "tainted" by bankruptcy or as a rare opportunity to acquire museum-quality pieces.
3. The End of an Era for Multi-Strategy Funds
The collapse of Weiss Multi-Strategy Advisers is part of a broader trend of consolidation and struggle within the hedge fund industry. Smaller and mid-sized firms have found it increasingly difficult to compete with "platform" giants like Citadel or Millennium. The sale of Weiss’s art is the final, visual coda to the dissolution of a firm that once stood as a symbol of 1980s-era financial ambition.
4. The IRS and the "Waterfall"
The $180 million IRS debt looming in the background suggests that even a successful auction at Sotheby’s may not be enough to make all parties whole. This case will likely set precedents for how art-secured debt is treated in relation to federal tax liens in complex bankruptcy proceedings.
As November approaches, the art world will be watching Sotheby’s with bated breath. The sale of George Weiss’s collection is not just an auction; it is a $123 million litmus test for the resilience of the art market and a final accounting for a titan of the hedge fund era.