By Staff Reporter
September 18, 2026
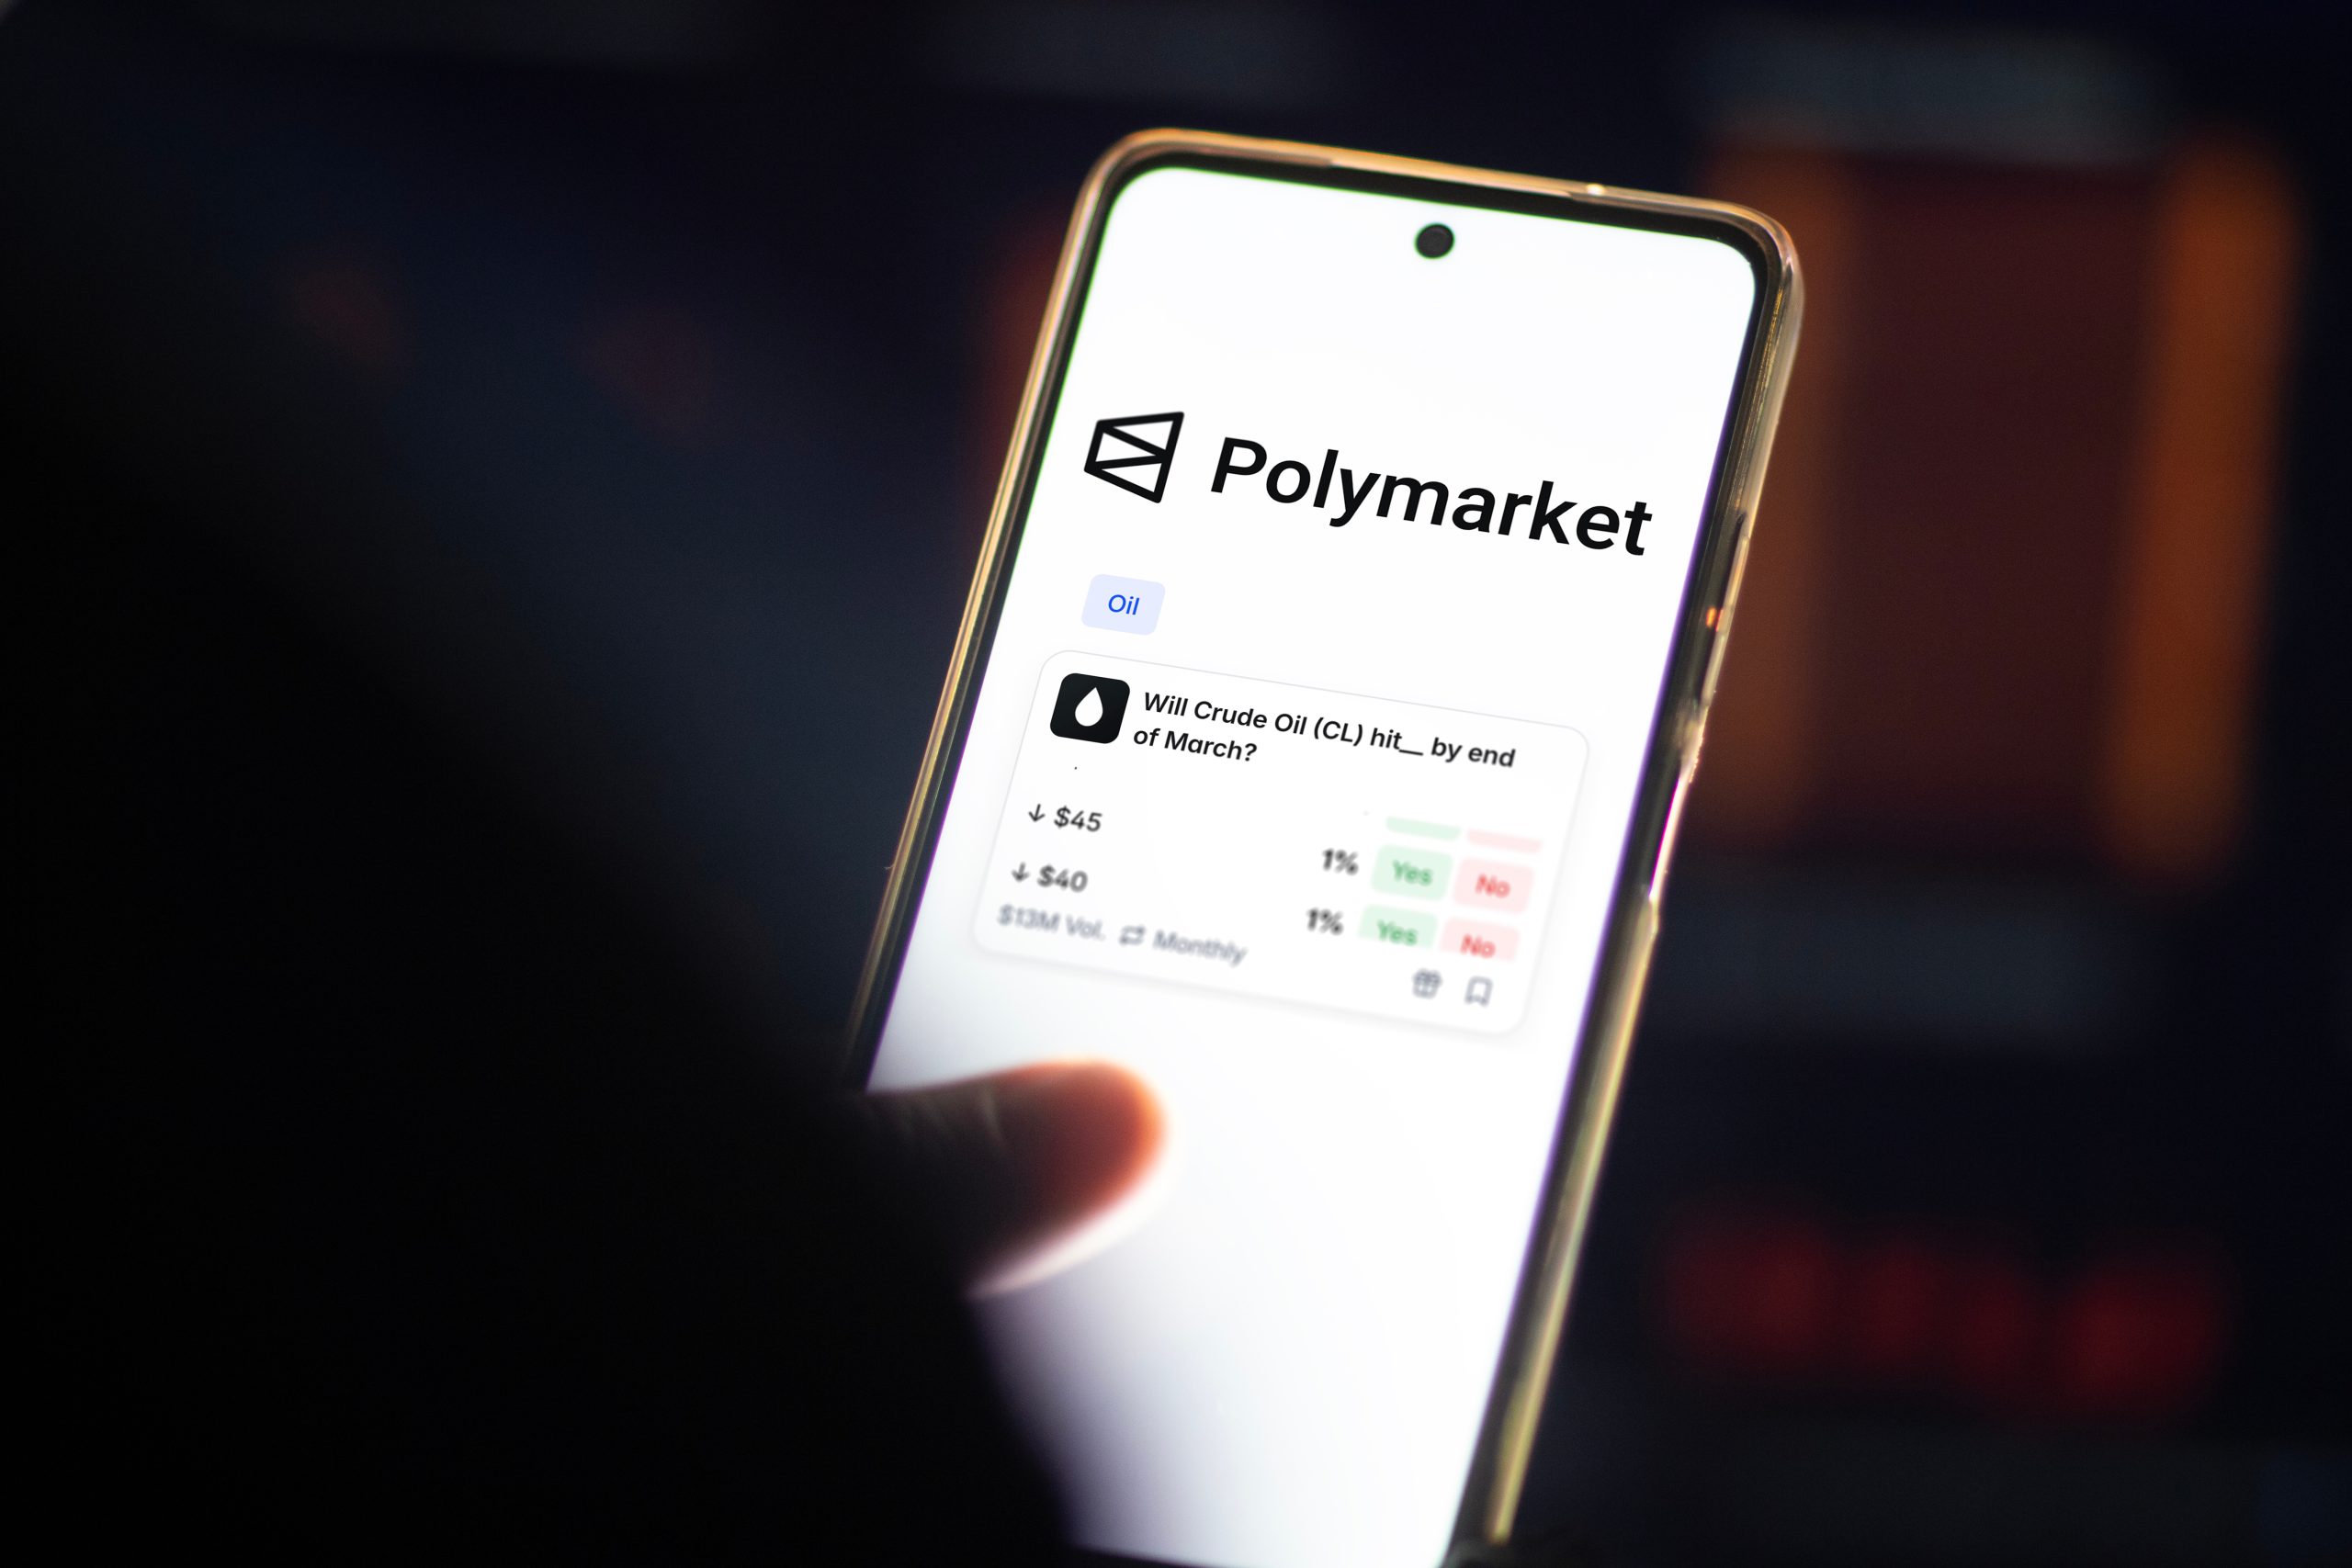
The landscape of corporate compliance and regulatory oversight is undergoing a seismic shift. As U.S. enforcement authorities—led by the Securities and Exchange Commission (SEC) and the Department of Justice (DOJ)—intensify their focus on the burgeoning prediction-markets space, a new and troubling case of alleged insider trading has emerged. This time, the allegations implicate an employee of the global accounting and professional services giant, KPMG.
This incident arrives at a precarious moment for the accounting profession, which is already grappling with increased expectations regarding ethical standards, data integrity, and the prevention of market manipulation. As investigators dig deeper into this latest breach of fiduciary duty, the case serves as a stark reminder of the persistent threat posed by "insider misuse of information" in an era of hyper-connected digital finance.
The Core Facts: A Breach of Professional Trust
The allegations center on an individual employed by KPMG who is accused of exploiting non-public information obtained through their professional capacity to gain an unfair advantage in the securities markets. While specific details of the trades and the nature of the information remain under seal as the investigation progresses, the core accusation mirrors traditional insider trading patterns: the utilization of confidential, material information before it is disseminated to the public.
For a firm like KPMG, which occupies a position of gatekeeper status in the global financial ecosystem, such allegations are not merely individual transgressions; they represent a significant reputational risk. The integrity of the capital markets relies heavily on the premise that those with access to sensitive corporate data—auditors, consultants, and tax advisors—adhere to the highest standards of confidentiality. When that trust is violated, it ripples through the entire client base and challenges the regulatory framework intended to ensure a level playing field.
Chronology of Regulatory Interest
The trajectory of this investigation is part of a broader, accelerating trend in regulatory enforcement. To understand the gravity of the current situation, one must look at the timeline of events leading up to this point:
- Q1 2026: Increased Scrutiny on Prediction Markets: Federal regulators began explicitly signaling that the rise of prediction-market platforms would not grant users immunity from insider trading laws. Warnings were issued to institutional investors regarding the use of "alternative data."
- Summer 2026: Preliminary Monitoring: SEC surveillance units reportedly flagged irregular trading patterns linked to accounts associated with several high-profile firms, including professional services providers.
- August 2026: Internal Discovery: KPMG reportedly identified anomalous activity during routine internal compliance audits, triggering an internal investigation and subsequent self-reporting to federal authorities.
- Mid-September 2026: The formal inquiry gained momentum as federal investigators moved to secure records, leading to the current public acknowledgment of the investigation.
Supporting Data: The Expanding Scope of Insider Trading
The urgency behind this case is supported by a growing body of data regarding white-collar crime. According to reports from the SEC’s Division of Enforcement, insider trading cases have seen a 14% uptick in the last fiscal year, with a notable shift toward cases involving "digital footprints" and decentralized financial markets.
The Role of Prediction Markets
Prediction markets—platforms where individuals bet on the outcomes of future events, such as corporate earnings or regulatory decisions—have become a "wild west" for regulators. Because these platforms often operate with less stringent disclosure requirements than traditional stock exchanges, they have become magnets for individuals looking to profit from proprietary knowledge.
Professional Services at Risk
Data indicates that employees at "Big Four" accounting firms are frequently targeted by bad actors, or become bad actors themselves, because of their unique access to:
- Earnings Pre-releases: Audited figures that have not yet been filed with the SEC.
- M&A Activity: Confidential details regarding upcoming mergers and acquisitions.
- Regulatory Changes: Insight into upcoming compliance shifts that could affect a company’s valuation.
Official Responses and Corporate Stance
In response to the unfolding investigation, KPMG has maintained a posture of full cooperation with federal authorities. While the firm has not released the name of the employee, a spokesperson confirmed that the individual has been placed on leave pending the outcome of the investigation.
"KPMG holds its professionals to the highest ethical standards," a statement from the firm read. "We are committed to transparency and are working closely with the relevant regulatory bodies to resolve this matter. We have rigorous internal controls in place, and we are currently reviewing those systems to ensure that our commitment to market integrity remains unwavering."
Regulators, meanwhile, have remained characteristically tight-lipped. An SEC spokesperson stated, "We do not comment on ongoing investigations. However, our message remains clear: the source of the insider information—whether it comes from a boardroom, an audit desk, or a prediction platform—is immaterial. If you trade on non-public information, you are violating the law."
Implications: A New Era of Compliance
The implications of this case are profound, likely forcing a wholesale reassessment of how professional services firms manage internal data.
1. The "Gatekeeper" Liability
Accountants and auditors are increasingly viewed by regulators as the first line of defense against market fraud. This incident suggests that firms may face higher levels of "gatekeeper liability" if they cannot demonstrate that they have effectively siloed sensitive client data. We may see a shift toward more aggressive "zero-trust" architecture within accounting firms, where access to client financial data is restricted to the bare minimum number of personnel.
2. Enhanced Monitoring of Personal Accounts
It is highly probable that KPMG and its competitors will move toward stricter mandates regarding employee personal trading. This may include mandatory disclosures of all brokerage accounts, real-time automated monitoring of employee trading activity, and potentially even restrictions on trading in sectors where the firm provides audit services.

3. The Regulatory "Chilling Effect"
The aggressive stance taken by the DOJ and SEC could have a "chilling effect" on the industry. While this serves to deter misconduct, it may also lead to a more cautious, risk-averse environment where the flow of information necessary for efficient audit processes becomes burdened by bureaucratic hurdles.
4. Legal Precedent
This case will likely be closely watched as a bellwether for how the courts interpret the intersection of "prediction markets" and "material non-public information." If the government secures a conviction, it will solidify the legal precedent that insider trading laws apply to any venue where speculative betting takes place, provided the information used was obtained through a breach of duty.
Conclusion: Lessons for the Future
As the investigation into the KPMG employee continues, the broader message for the corporate world is unmistakable: the regulatory walls are closing in. No sector is exempt from the mandate of market fairness, and the digital age has provided regulators with unprecedented tools to track illicit gains.
For organizations, the primary lesson is that internal compliance policies must evolve faster than the methods used to exploit them. As prediction markets and other novel financial instruments continue to grow in popularity, firms must ensure that their employees understand that the ethical boundaries of the office extend to every digital platform they inhabit.
The coming months will likely see a flurry of new guidance from the SEC and the PCAOB (Public Company Accounting Oversight Board) regarding the handling of sensitive data by auditors. For now, the KPMG case serves as a sober reminder that in the world of high-stakes finance, the most valuable asset any professional possesses is not their knowledge, but their reputation for integrity. When that is compromised, the cost is far greater than any illicit profit could ever justify.

The industry will be watching closely, waiting to see if this is an isolated incident or the harbinger of a new regulatory crackdown on the professional services sector. One thing is certain: the era of lax internal oversight is coming to a definitive end.