By Kai Guo | October 13, 2026
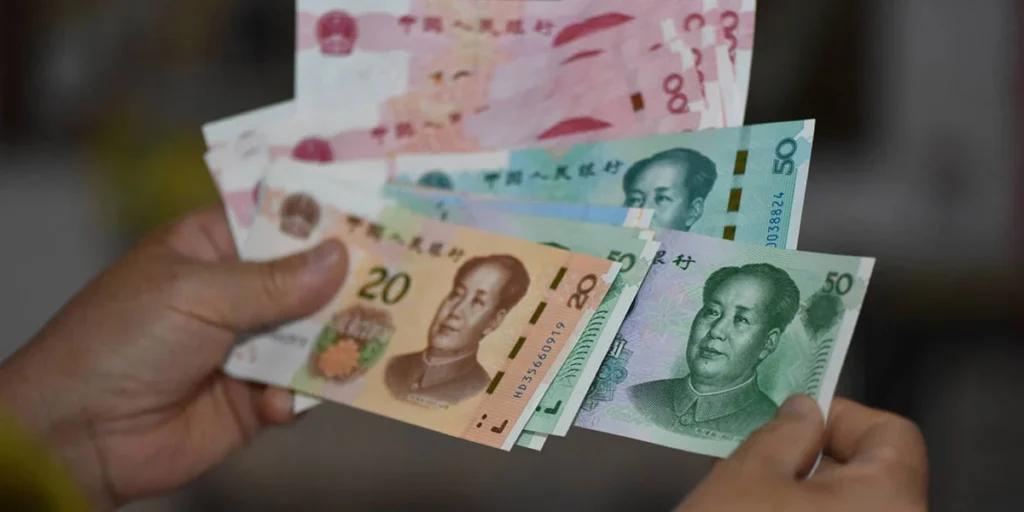
The global financial architecture is once again grappling with an old ghost in a new machine. As the world navigates a complex economic landscape in late 2026, the renminbi (RMB) has returned to the epicenter of geopolitical and macroeconomic discourse. With China’s merchandise trade surplus reaching a staggering $1.2 trillion in 2025, the chorus of international voices calling for a significant revaluation of the Chinese currency has reached a fever pitch.
However, beneath the surface of these calls for appreciation lies a fundamental misunderstanding of the Chinese economic engine. To treat the renminbi as the primary lever for correcting global imbalances is to mistake the symptom for the disease. The currency’s weakness is not a calculated predatory act, but a reflection of profound structural lethargy within China’s domestic demand.
The Core Argument: Beyond the Exchange Rate Myth
The prevailing consensus among Western financial commentators and policymakers is deceptively simple: China’s trade surplus is a direct result of an artificially suppressed renminbi. The argument posits that by keeping its currency undervalued, Beijing is effectively subsidizing its exports while curbing imports, thereby exporting deflationary pressures to its trading partners.
Yet, this narrative ignores the internal reality of the Chinese economy. The RMB’s current valuation is a mirror held up to China’s domestic malaise—specifically, the persistent weakness in household consumption and the ongoing deleveraging of the property sector. Forcing a sharp currency appreciation without first stimulating domestic demand would be a pyrrhic victory. It would likely cripple China’s export sector, exacerbate domestic unemployment, and trigger a deflationary spiral that would ultimately harm, rather than help, the global economy.
Chronology: The Path to the $1.2 Trillion Surplus
To understand the current tension, one must examine the timeline that led to the record-breaking trade surplus of 2025.
- 2022–2023: The Post-Pandemic Divergence: While Western economies faced inflationary shocks, China experienced a sluggish recovery marked by low consumer confidence and a property market crisis.
- 2024: The Manufacturing Pivot: As domestic demand failed to pick up, Beijing doubled down on "New Quality Productive Forces," prioritizing high-end manufacturing—specifically electric vehicles (EVs), solar panels, and lithium-ion batteries—to drive growth.
- 2025: The Surplus Milestone: Driven by a highly competitive manufacturing base and stagnant domestic consumption, China’s exports surged. The trade surplus hit $1.2 trillion, fueling accusations of "overcapacity" from the United States, the European Union, and emerging market peers.
- Early 2026: The Calls for Revaluation: International financial institutions and think tanks, such as the Council on Foreign Relations, began publishing research suggesting the RMB is undervalued by as much as 30%.
- Q3 2026: The Diplomatic Friction: Tensions in the G20 and bilateral trade forums have escalated, with protectionist rhetoric reaching its highest level since the mid-2010s.
Supporting Data: Dissecting the Imbalance
The data underpinning the "undervaluation" argument is compelling but incomplete.
The Trade Surplus vs. Domestic Consumption
The $1.2 trillion surplus is not merely a product of exchange rates; it is a product of the savings-investment gap. In China, the household share of GDP remains historically low, hovering around 40%, compared to the global average of nearly 60%. When households save more and consume less, the excess production must find a home in foreign markets.
Manufacturing Dominance
Data from the National Bureau of Statistics (China) shows that while retail sales have lagged, industrial value-added growth has remained robust. This divergence is the structural core of the imbalance. If China were to appreciate its currency today, the export sector would suffer, but the lack of internal demand would remain, leading to a reduction in output rather than a pivot toward domestic consumption.
Official Responses and Strategic Stances
The Beijing Perspective: "Stability is Paramount"
The People’s Bank of China (PBOC) has maintained a cautious stance. Official communiqués emphasize a "market-based exchange rate" while simultaneously hinting at "counter-cyclical adjustments" to prevent excessive volatility. Beijing views the renminbi as a tool for internationalization rather than a weapon for trade, arguing that the currency’s value is determined by the "fundamental health" of the economy.
The Western Response: "Leveling the Playing Field"
In Washington and Brussels, the sentiment is hardening. Treasury officials and trade representatives have begun to explicitly link currency valuation to trade fairness. The rhetoric has shifted from "market access" to "macroeconomic rebalancing," suggesting that currency appreciation is a prerequisite for any meaningful trade cooperation.
Implications: What Happens Next?
If the current trajectory continues, we face three potential scenarios for the global economy.
1. The Protectionist Trap
Should China refuse to adjust its currency, and should the West impose aggressive tariffs or sanctions, we risk a "Great Decoupling." This would fracture global supply chains, drive up costs for consumers worldwide, and likely trigger a global recession as manufacturing efficiencies are lost to geopolitical fragmentation.
2. The Domestic Reform Path
If Beijing pivots to aggressively stimulate household income—perhaps through direct transfers, a stronger social safety net, and a decoupling of social benefits from household registration (hukou)—the reliance on exports would naturally diminish. This is the most desirable outcome, as it would naturally balance the trade account without requiring a blunt instrument like currency manipulation.
3. The Controlled Devaluation (The Risk Scenario)
If China succumbs to international pressure and allows the RMB to appreciate sharply without domestic support, the result could be a domestic economic collapse. A rapid rise in the currency would bankrupt export-oriented firms that operate on razor-thin margins. The subsequent spike in unemployment would suppress consumer demand even further, creating a vicious cycle of stagnation.
Conclusion: A Holistic Approach to Rebalancing
The narrative that a "stronger renminbi" is a panacea for the world’s economic woes is a dangerous simplification. It assumes that China can simply flip a switch and transform from an export-led economy to a consumption-led one.
Global imbalances are, by definition, a two-way street. They are the result of high savings and low consumption in Asia, coupled with high consumption and low savings in the West. Focusing exclusively on the renminbi ignores the structural necessity for the United States and Europe to address their own fiscal deficits and productivity challenges.
For the international community, the goal should be to encourage China to reform its domestic distribution of wealth. For Beijing, the goal must be to recognize that its current export-led model is reaching a limit—not because of the currency’s value, but because the world can no longer absorb its surplus production.
Addressing this imbalance requires a sophisticated dialogue that goes beyond exchange rates. It requires a fundamental shift in how China interacts with its own citizens and how the world interacts with the Chinese market. Without this, we are destined to repeat the cycles of friction that have defined the last decade, with each iteration bringing us closer to a global economic rupture that no one can afford.
The renminbi is not the villain of this story; it is simply the loudest voice in a room where the structural foundations are creaking. The path forward is not found in the currency markets, but in the halls of policy where domestic demand, structural reform, and global cooperation intersect.