By [Your Name/Journalistic Staff]
October 9, 2026
For decades, the financial architecture governing African sovereign debt has operated under a persistent, systemic anomaly. While nations across the continent have modernized their regulatory frameworks, diversified their economies, and navigated volatile global markets, their borrowing costs have remained tethered to the assessments of the "Big Three" credit rating agencies (CRAs): Fitch, Moody’s, and S&P. Critics argue these agencies utilize methodologies that are not only opaque but fundamentally misaligned with the economic realities of African markets.
However, a shift is underway. The establishment of the Africa Credit Rating Agency (ACRA)—a pan-African initiative designed to provide a more nuanced, context-aware assessment of sovereign risk—represents a potential turning point. By challenging the hegemony of global agencies, ACRA aims to dismantle the "risk premium" that has historically stifled development across the continent.
The Core Problem: A Mismatch in Methodology
To understand the urgency of this initiative, one must look at the structural disconnect in current rating practices. As Hannah Wanjie Ryder aptly puts it, the current system is akin to taking an exam and answering every question correctly, only to fail because the evaluator is using an answer key for a completely different test.
Major international agencies rely heavily on quantitative models optimized for developed Western economies. These models prioritize metrics such as historical debt-to-GDP ratios and rigid fiscal deficit targets. When applied to African nations, these criteria often ignore structural strengths—such as natural resource wealth, demographic dividends, and ongoing institutional reforms—while disproportionately penalizing temporary liquidity crunches.
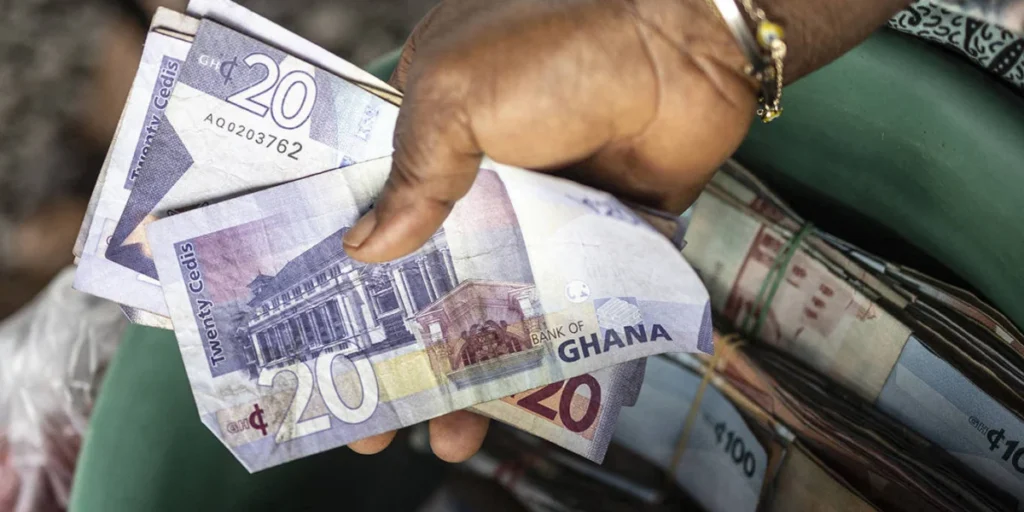
This leads to a "subjective risk premium." African countries are often assigned lower ratings than their objective economic fundamentals might suggest. Consequently, they pay significantly higher interest rates to access international capital markets, creating a debt trap where a substantial portion of national budgets is diverted to interest payments rather than infrastructure, education, or healthcare.
A Chronology of the Sovereign Debt Dilemma
The move toward an indigenous rating agency did not emerge in a vacuum. It is the result of a long-standing frustration with the global financial status quo.
- 1990s–2000s: The rise of the Big Three as the arbiters of global creditworthiness. African nations, beginning to access Eurobond markets, are forced to submit to these ratings to gain investor confidence.
- 2008–2010: The Global Financial Crisis exposes the fallibility of rating agencies, yet their influence over emerging markets remains largely unchecked.
- 2015–2020: Several African nations experience "rating shocks"—sudden downgrades that trigger capital flight and spiking borrowing costs, even during periods of relative domestic political stability.
- 2022: The African Union (AU) intensifies discussions regarding the formation of a sovereign credit rating agency to mitigate the "biased perception" of African risk.
- 2024–2025: Technical feasibility studies are completed, and initial capital mobilization begins, supported by regional development banks and private institutional investors.
- October 2026: The Africa Credit Rating Agency (ACRA) moves into its operational phase, signaling a new era of financial sovereignty.
Supporting Data: The Cost of Bias
The economic implications of current rating methodologies are profound. Data from the African Development Bank (AfDB) suggests that "perceived risk" costs the continent billions in unnecessary interest payments every year.
- The "African Premium": Studies indicate that African sovereigns pay an average of 200 to 400 basis points more than similarly rated entities in other parts of the world.
- Debt Servicing: In some sub-Saharan African nations, interest payments now consume upwards of 30% of total government revenue. This is a direct consequence of credit ratings that force these countries to borrow at double-digit yields.
- Capital Flow Volatility: When a global agency issues a "negative outlook," it often triggers automated sell-offs by institutional investors who rely on passive, algorithmic trading. These sudden outflows can destabilize local currencies and force central banks into costly interventions.
By introducing an agency that understands local institutions—such as the role of regional trade blocs or the impact of climate-resilient infrastructure projects—ACRA aims to narrow this spread, potentially saving the continent billions in annual debt servicing costs.
Official Responses and Stakeholder Perspectives
The initiative has met with a complex reception from the global financial community.
The Proponents’ View
Advocates, including policymakers from the African Union and the UN Economic Commission for Africa (UNECA), argue that ACRA is a necessary corrective. "This is not about avoiding accountability," says a senior spokesperson for the initiative. "It is about ensuring that the assessment process reflects the actual performance of our economies. We are not asking for a ‘pass’; we are asking for an accurate ‘grade’ based on the reality of our development trajectory."
The Skeptical View
Representatives from international financial institutions and some Western investment banks have expressed caution. The concern is that a regional agency might be viewed as less independent or subject to political pressure from member states. "Credit ratings derive their value from their perceived neutrality and global comparability," notes a lead analyst at a major London-based investment firm. "If an agency is perceived as a ‘cheerleader’ for the region, international investors may be hesitant to accept its ratings as a primary benchmark."
The Compromise
The architects of ACRA are aware of these concerns. The agency is being structured with a governance model that ensures independence from the AU and individual governments, utilizing a board of international experts and stringent, transparent criteria that align with international best practices (IOSCO standards).
Implications: A New Financial Architecture
The operationalization of ACRA carries significant implications for the future of African economics.
1. Market Diversification
If ACRA succeeds in building credibility, it will encourage the growth of local currency bond markets. By providing reliable information to domestic institutional investors (like pension funds), African nations can rely less on volatile international dollar-denominated debt.
2. Enhanced Transparency
The competition introduced by ACRA will likely force the Big Three to improve their own methodologies. As they face a competitor that provides more granular data on African markets, the global agencies may be compelled to refine their analytical tools to avoid losing their relevance in one of the world’s fastest-growing regions.
3. Long-term Economic Sovereignty
Perhaps the most significant implication is the psychological and strategic shift in how African nations interact with global capital. By owning the process of risk assessment, African policymakers are asserting a greater degree of control over their economic destinies. It represents a move away from being passive subjects of global financial judgments toward becoming active participants in setting the standards by which their growth is measured.
Conclusion: The Path Forward
The launch of the Africa Credit Rating Agency is not a panacea for the continent’s economic challenges. It cannot eliminate the risks associated with global commodity price fluctuations, climate change, or political instability. However, it addresses a fundamental distortion in the global financial system—a distortion that has acted as a persistent drag on Africa’s potential.
As ACRA begins its work, the eyes of the global investment community will be on its methodologies. If it can prove that its ratings are as robust and objective as those of its competitors, it will do more than just lower borrowing costs; it will validate the idea that Africa’s economic narrative should be written, analyzed, and understood by those who live it. The exam is finally being graded with the correct answer key.