The retail landscape is shifting beneath our feet, defined by a curious tension between nostalgia-driven marketing and a stark, economically driven caution. This week’s industry pulse reveals a sector grappling with the consequences of inflation, the evolving digital-physical divide, and the undeniable influence of corporate activism on the American consumer.
Whether it is the resurgence of print media as a branding tool, the painful necessity of store closures, or the anxiety surrounding big-ticket electronic sales, the current retail environment is a masterclass in adaptation. Below, we dissect the critical developments of the week, analyzing what these trends signal for the future of commerce.
1. The Main Facts: A Diverse Week in Retail
The week was dominated by a series of high-profile pivots. The most notable shift in brand strategy came from Revolve, which is betting that in a world of infinite scrolling, the tactile experience of a physical magazine can provide the "long-form" connection that modern consumers crave. Conversely, the brick-and-mortar sector faced a sobering reminder of economic reality as Cato announced a significant acceleration in its store closure program.
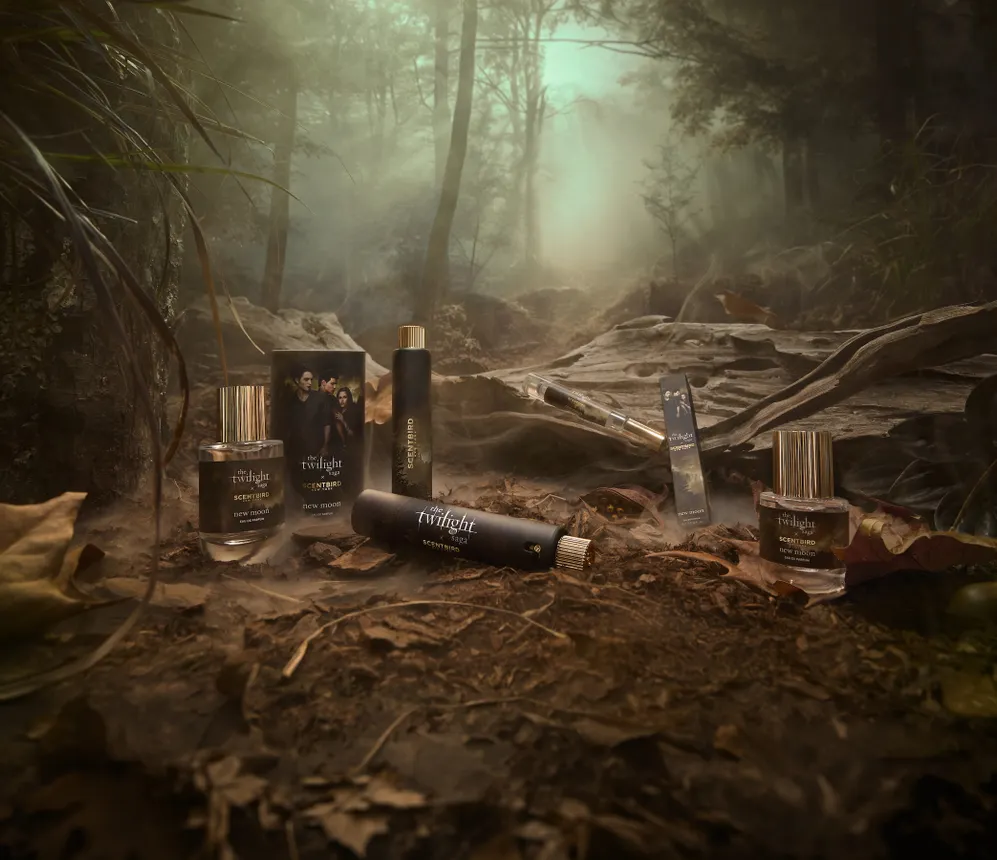
Simultaneously, the "retail therapy" segment saw a pop-culture infusion with Scentbird’s latest Twilight collaboration, highlighting the power of fandom-driven product drops. Perhaps most significantly, the intersection of retail and civic duty took center stage through Patagonia’s aggressive, multi-million dollar "Get Out the Vote" campaign, proving that for some brands, the bottom line is inextricably linked to the ballot box.
2. Chronology: A Week of Highs and Lows
Tuesday: Revolve officially announced the launch of Revolve Magazine, signaling a pivot toward traditional editorial content to deepen customer engagement.
Wednesday: Analysts at Jefferies released a sobering note regarding Best Buy’s outlook, citing the Conference Board’s latest consumer confidence report, which highlights a sharp decline in interest for big-ticket electronics.
Thursday: Scentbird and Lionsgate capitalized on the Halloween season, launching "The Twilight Saga: New Moon" eau de parfum, aimed at capturing the nostalgia and intensity of the popular franchise.
Late Week: Cato confirmed that it will shutter an additional 70 stores, bringing its total annual closures to 120, as it attempts to insulate the brand from the pressures of diminished discretionary income among its core customer base.
3. Supporting Data and Market Analysis
The data emerging from this week’s reports tells a story of divergence.
The Cato Contraction
Cato’s decision to close 70 stores in the third and fourth quarters is a direct response to a challenging macroeconomic climate. The company expects to incur exit costs between $1 million and $1.3 million. However, the move is a strategic retreat: by shedding underperforming assets, Cato intends to stabilize its balance sheet and improve operating margins by fiscal 2027. This highlights the current retail "purge" strategy, where legacy chains are sacrificing footprint to ensure long-term solvency.
The TV Tech Stagnation
The Jefferies report on Best Buy is perhaps the most concerning for the electronics sector. According to the Conference Board, only 9% of consumers intend to purchase a television in the next six months—a nearly 3-point drop from February. This decline is particularly alarming for Best Buy, where televisions represent approximately 20% of their sales base. Even with the introduction of high-end RGB LED technology, the analysts suggest that "stretched wallets" are currently overriding the desire for technological upgrades.
4. Official Responses and Corporate Strategy
Revolve’s "Slow Down" Strategy
Michael Mente, co-founder and co-CEO of Revolve Group, offered a unique justification for the company’s return to print. In an era dominated by short-form video and rapid-fire social media content, Mente argues that the brand needs a vehicle for a "longer conversation."
"In a world that’s increasingly short-form and digital, we wanted to create something that lets us slow down and have a longer conversation with our customers," Mente stated.
The magazine is designed as a "physical manifestation" of the Revolve brand—a move intended to cement the company’s status as a lifestyle authority rather than just an e-commerce storefront.
The Patagonia Activism Model
Patagonia’s latest initiative is a masterclass in high-stakes corporate advocacy. By spending $11.2 million in just four days, the company successfully reached 112,000 individuals to encourage voter turnout. This is not a new behavior for the brand; since 2016, Patagonia has closed its offices and warehouses on Election Day. By framing their environmental mission as a legislative goal, they are leveraging their brand equity to mobilize their consumer base in a way few other retailers dare to attempt.
5. Implications: What This Means for the Future
The Return of the Physical Narrative
Revolve’s foray into print is a reaction to digital fatigue. As social media algorithms become more opaque and advertising costs rise, brands are finding that "owned" physical media—like high-quality magazines—can foster a sense of exclusivity and permanence. We should expect to see more digital-first retailers testing physical media as a "premium" touchpoint for their most loyal customers.
The Fragility of Big-Ticket Discretionary Spending
The downward trend in TV purchase intent is a bellwether for the broader electronics industry. When consumers stop upgrading home entertainment hardware, it is often a lagging indicator of broader economic anxiety. Best Buy’s gamble on new tech, such as RGB LED displays, will serve as a test case for whether premium innovation can overcome a period of reduced consumer confidence. If customers are ignoring new, high-end display technology, it suggests that the "replacement cycle" for home goods has been significantly extended.
The "Spooky Season" Revenue Model
Scentbird’s collaboration with the Twilight franchise represents a growing trend in retail: the "fandom drop." By aligning a product with a specific cultural moment (in this case, the seasonal obsession with Twilight), retailers are creating high-velocity, low-risk revenue streams. These niche collaborations allow brands to tap into highly engaged communities, providing a buffer against the general downturn in broad-market consumer spending.
The Hard Truth of Store Closures
Cato’s situation serves as a warning to mid-market retailers. The combination of inflation, rising fuel costs, and stagnant wages for lower-to-middle-income demographics is creating a "death valley" for brick-and-mortar stores that rely on discretionary spending. For these retailers, the only path to survival is an aggressive audit of the store portfolio. We are likely to see more announcements of "additional closures" across the industry as companies pivot toward smaller, more efficient footprints.
Final Thoughts: The Road Ahead
As we look toward the remainder of the year, the retail sector finds itself in a period of intense recalibration. The successful brands will be those that can master the duality of the current market: the need for high-touch, emotional connections (like Revolve’s magazine) and the cold, hard necessity of operational efficiency (like Cato’s store closures).
The upcoming election on November 3 will be a significant pivot point for consumer sentiment. With Patagonia’s massive mobilization efforts and the broader economic anxiety reflected in the Jefferies/Best Buy report, the industry is bracing for a holiday season that will be defined by careful spending, selective consumption, and an heightened focus on brand values. Retailers are no longer just selling products; they are navigating a complex cultural and economic ecosystem where every store opening, product launch, and political stance is scrutinized by an increasingly cautious public.