By Kenneth Rogoff
October 1, 2026
The metaphor of a runaway train has long been a staple of political discourse, but when applied to the United States’ current fiscal trajectory, it is no longer merely a rhetorical flourish—it is an accurate description of a looming economic reality. As the federal deficit holds steady at approximately 6% of GDP despite a period of ostensibly solid economic growth, the American economy resembles a locomotive hurtling along a twisting mountain track, with engineers who fear that slowing down will cost them their tenure.
High debt levels are not inherently catastrophic, but they become perilous when the confluence of rising interest rates and institutional paralysis creates a "fiscal trap." When governments lose the capacity to respond to exogenous shocks—whether they be military conflicts, deep recessions, or systemic financial crises—the danger is no longer theoretical; it is imminent.
The Anatomy of the Crisis: Main Facts
The United States is currently navigating a period of fiscal expansion that defies traditional economic cycles. Historically, governments have utilized periods of robust growth to consolidate debt and build "fiscal space." Today, however, the U.S. federal government is running a deficit that would be alarming during a recession, let alone during a time of expansion.
The core of the problem lies in the structural imbalance between federal revenue and mandatory spending. With the debt-to-GDP ratio reaching historic highs, the cost of servicing that debt has become one of the largest line items in the federal budget. As interest rates remain elevated to combat persistent inflationary pressures, the "crowding out" effect—where government borrowing absorbs capital that would otherwise fund private investment—is beginning to dampen long-term productivity.
The political economy of this situation is equally fraught. There is currently little appetite in Washington to engage in the necessary, albeit politically painful, work of deficit reduction. Instead, the current administration, under President Donald Trump, has shown a distinct preference for maintaining fiscal stimulus, operating under the assumption that growth will eventually outpace debt accumulation.
A Chronology of Fiscal Drift
To understand how the United States arrived at this juncture, one must look back at the shifting attitudes toward debt over the last two decades.
- 2008–2010: The Great Recession: The initial response to the global financial crisis involved significant deficit spending. At the time, this was viewed as a temporary, necessary intervention to prevent a total economic collapse.
- 2017–2019: Tax Reform and Expansion: The Trump administration’s 2017 tax cuts, while intended to spur investment, significantly reduced federal revenue. During this period, the debt continued to climb even as the economy hit record levels of low unemployment.
- 2020–2022: The Pandemic Response: The COVID-19 pandemic necessitated unprecedented levels of fiscal support. Trillions of dollars were injected into the economy, effectively bridging the gap between a shutdown and recovery, but leaving a permanent, higher floor for federal spending.
- 2023–2025: The Inflationary Pivot: As inflation surged, the Federal Reserve was forced to raise interest rates aggressively. This created a "scissors effect": revenue remained stagnant or grew slowly, while the cost of servicing the national debt skyrocketed due to higher borrowing costs.
- 2026: The Current Stasis: As of October 2026, the U.S. finds itself in a state of political paralysis, where neither party is willing to propose the tax hikes or entitlement reforms necessary to stabilize the trajectory.
Supporting Data: The Arithmetic of Unsustainability
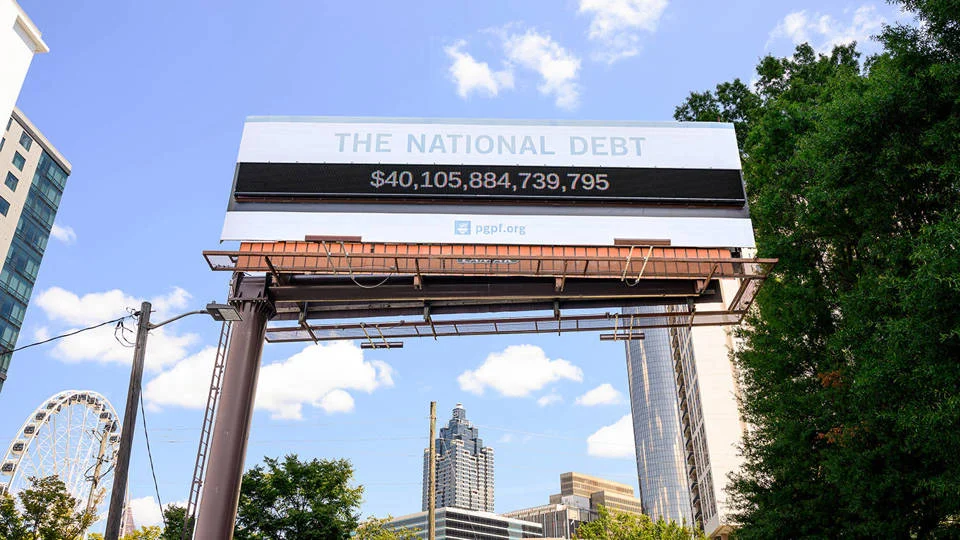
The numbers behind the current fiscal situation are sobering. A deficit of 6% of GDP during a growth cycle is unprecedented in American history, outside of wartime.
Interest Rate Sensitivity
The federal government is currently paying significantly more in interest on the national debt than it was even three years ago. Because a large portion of the debt is short-term, the government is forced to "roll over" its obligations at current, higher market rates. This creates a feedback loop: the government borrows more money to pay the interest on the debt it already has, which increases the total debt, which in turn increases the interest payments.
Productivity and Growth
Critics of austerity argue that as long as the economy grows, the debt is manageable. However, the data suggests that federal spending is increasingly directed toward consumption rather than investment. If the capital being borrowed does not lead to a commensurate increase in GDP growth, the economy effectively becomes a Ponzi scheme of sovereign debt—relying on new debt to pay off old obligations.
Official Responses and Political Inertia
The silence from the executive branch regarding fiscal sustainability is deafening. President Trump’s approach to the economy remains rooted in a belief that growth can be engineered through deregulation and tax incentives. When asked about the ballooning deficit, the official response is consistently focused on the "upside" of the economy—emphasizing that as long as the labor market is strong, the debt is a secondary concern.
Congressional Republicans, historically the "party of fiscal responsibility," have largely abandoned the cause of deficit reduction in favor of maintaining the tax cuts of the previous administration. Meanwhile, the Democratic caucus remains divided, with some members advocating for higher corporate taxes to fund social programs, while others fear that such measures would stifle the very growth the administration relies upon to keep the debt-to-GDP ratio from exploding.
The Federal Reserve, led by its governors, has remained technically independent but finds itself in an impossible position. They are tasked with maintaining price stability through high interest rates, which directly contradicts the Treasury’s need for low-interest-rate financing to sustain the deficit. This tension between fiscal policy (government spending) and monetary policy (interest rates) is the hallmark of a state in fiscal distress.
The Implications: A World of Limited Options
What happens when the "train" reaches the end of the line? The implications are grave.
The Loss of Policy Flexibility
The most immediate danger is the loss of "fiscal firepower." In the event of a significant global crisis—a major war, a pandemic, or a financial meltdown—the U.S. will no longer have the luxury of borrowing its way out of the problem. If the debt-to-GDP ratio is already at a breaking point, the bond markets may demand much higher premiums to lend to the U.S. government, potentially leading to a sovereign debt crisis that would make the 2008 crash look mild by comparison.
The Crowding Out Effect
As the government becomes the primary borrower in the capital markets, interest rates for private companies and individuals will remain artificially high. This discourages the very innovation and business expansion that the country needs to grow its way out of its debt problems. We are essentially sacrificing the future productivity of the private sector to pay for the present consumption of the public sector.
The Erosion of Global Trust
The U.S. dollar’s status as the world’s reserve currency is predicated on the belief that the United States is a "safe haven" for capital. If the world loses faith in the U.S. government’s ability to manage its finances, the demand for Treasuries will decline. This would force the Federal Reserve to choose between two catastrophic options: either let interest rates rise to levels that would trigger a deep depression, or print money to buy the debt, which would lead to runaway inflation.
Conclusion: The Need for a New Direction
The current fiscal trajectory is not a mystery; it is a choice. We are choosing to prioritize short-term political comfort over long-term stability. The train is indeed hurtling down a mountain, and while the scenery may look pleasant for the moment, the track ahead is broken.
To avoid a crash, the United States must embark on a multi-pronged approach:
- Entitlement Reform: Addressing the long-term liabilities of Social Security and Medicare, which represent the largest drivers of long-term federal spending.
- Revenue Realignment: A serious look at the tax code to ensure that the burden of supporting the state is shared equitably and that revenue streams are sufficient to cover core expenditures.
- Fiscal Rules: Implementing binding fiscal targets that force Congress to account for the impact of spending bills on the long-term debt.
The time for political grandstanding has passed. If Washington continues to ignore the math, the market will eventually force the issue—and the results will be far more painful than the modest reforms that could save us today. We are playing a dangerous game with the future of the American economy, and the clock is ticking.