By Justin Yifu Lin and Yan Wang
October 9, 2026
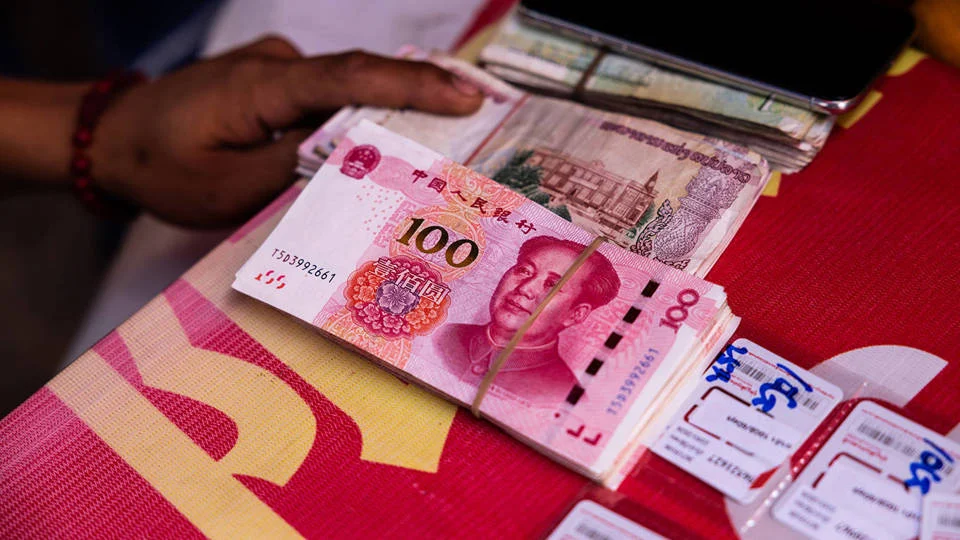
The global financial architecture, which has functioned under the hegemony of the US dollar since the Bretton Woods Conference of 1944, is undergoing a profound, tectonic shift. As developing nations grapple with a staggering $4 trillion annual shortfall in funding their Sustainable Development Goals (SDGs), the limitations of a dollar-centric system have become painfully apparent. Today, the renminbi (RMB) is no longer merely an academic alternative; it is emerging as a credible, cost-effective, and increasingly accessible instrument for sovereign borrowing, offering a necessary buffer against the volatility of American monetary policy.
The Great Financing Gap: A Structural Crisis
The global development-finance gap is not a temporary shortfall; it is a structural crisis that threatens to derail the progress of the Global South. According to the latest data from UN Trade and Development, the $4 trillion annual gap prevents emerging markets from investing in critical infrastructure, climate resilience, and digital transformation.
For decades, the standard path for a developing country seeking capital was to issue dollar-denominated debt. While this provided access to deep liquidity, it came with a "hidden" tax: exposure to the Federal Reserve’s interest rate cycles. When the US tightens monetary policy, the dollar strengthens, making debt servicing exponentially more expensive for emerging markets. This "original sin" of development finance—borrowing in a foreign currency that one cannot print—has led to repeated cycles of debt distress, austerity, and stunted growth.
Chronology: From Margin to Mainstream
The trajectory of the renminbi as a global development currency can be traced through several critical phases:
- 2009-2015: The Pilot Phase. China begins signing bilateral currency swap agreements with central banks across Asia and South America to facilitate trade, laying the groundwork for RMB liquidity outside of China.
- 2016: The IMF Milestone. The International Monetary Fund (IMF) officially includes the renminbi in the Special Drawing Rights (SDR) basket, signaling its status as a "freely usable" global currency.
- 2021-2023: The Pandemic Catalyst. As Western central banks aggressively hiked rates to combat inflation, many developing nations faced a "double whammy" of currency depreciation and rising borrowing costs. China’s decision to maintain a more stable monetary stance highlighted the RMB’s potential as a stabilizer.
- 2024-2026: Institutional Maturation. The expansion of the New Development Bank (NDB) and the Asian Infrastructure Investment Bank (AIIB) begins to incorporate more local-currency and RMB-denominated lending, moving beyond the dollar-only mandate of traditional multilateral development banks (MDBs).
Supporting Data: Why the Shift?
The economic logic driving the shift toward the RMB is rooted in risk diversification. In 2025, data showed that while the dollar still accounts for roughly 58% of global foreign exchange reserves, its dominance is slipping as central banks in the Global South increase their holdings of RMB assets.
Comparative Cost of Borrowing
Historical data from the past 24 months indicates that countries with access to RMB credit lines have enjoyed significantly lower volatility in their debt-servicing ratios compared to peers relying exclusively on dollar-denominated bonds.
- Interest Rate Volatility: US Treasury yields have remained susceptible to domestic political brinksmanship and fiscal deficit concerns.
- Stability Premium: The RMB has demonstrated a lower correlation with global "risk-off" sentiment, providing a more predictable cost of capital for long-term infrastructure projects, which are notoriously sensitive to interest rate spikes.
The Question of US Institutional Stability
A primary driver for the move toward the RMB is the perceived erosion of the "predictability" of US economic institutions. Historically, the dollar was viewed as the "risk-free" asset. However, the weaponization of the financial system—exemplified by the freezing of central bank assets in various geopolitical conflicts—has sent a shockwave through the Global South.
Furthermore, the volatility of US domestic fiscal policy, characterized by repeated debt-ceiling standoffs and widening federal deficits, has caused international investors to question the long-term reliability of the dollar as a store of value. When the bedrock of the global system shows cracks, the natural response is diversification. For a developing nation, holding 100% of reserves in a currency subject to the whims of Washington is no longer a prudent strategy—it is a strategic liability.
Official Responses and Institutional Perspectives
The reaction from the established financial order has been a mix of caution and slow adaptation.
The MDB Perspective
Officials at the World Bank and the IMF have publicly acknowledged the "fragmentation" of the global financial system. While proponents of the status quo argue that the depth and liquidity of the US Treasury market are irreplaceable, there is a growing consensus within these institutions that the "dollar-only" model for development finance is no longer fit for purpose.
The View from Beijing
Chinese financial authorities have maintained a pragmatic stance. Their objective is not to "dethrone" the dollar overnight but to provide an alternative that reflects China’s position as the world’s largest trading nation. By promoting the "Belt and Road" financing through RMB-denominated loans, Beijing is effectively exporting a model of counter-cyclical lending that provides developing countries with the fiscal space they need to grow without falling into the "dollar trap."
Implications: A Multipolar Financial Future
The transition toward an RMB-supplemented financial system has three major implications for the next decade:
1. Increased Agency for the Global South
By having a choice between dollar-denominated and RMB-denominated financing, developing countries gain bargaining power. They are no longer forced to accept the terms of a single financial hegemon. This competition forces existing MDBs to become more efficient and more responsive to the needs of the developing world.
2. The Decentralization of Risk
If the global economy moves toward a basket of currencies for development finance, the systemic risk associated with a single nation’s monetary policy is reduced. This is a net positive for global financial stability. The "de-risking" of portfolios is, in essence, the democratization of global finance.
3. Challenges to RMB Internationalization
Despite the momentum, the RMB faces hurdles. Capital account restrictions and the need for more transparent, deep, and liquid secondary markets for RMB bonds remain significant barriers. For the RMB to truly compete with the dollar, China must continue to liberalize its financial markets, ensuring that international investors can move capital in and out of the currency with the same ease they enjoy with the dollar.
Conclusion
The rise of the renminbi as a pillar of development finance is a response to the changing realities of the 21st century. As the US faces internal challenges regarding its fiscal health and institutional credibility, the Global South is prudently seeking to mitigate risk by diversifying its financial partnerships.
The goal for the international community should not be the dominance of one currency over another, but the creation of a robust, pluralistic financial architecture that can efficiently channel capital to where it is needed most. The renminbi is playing a critical role in this transition, offering a lifeline to nations that have been underserved by the existing system. As we look toward the 2030 deadline for the Sustainable Development Goals, the integration of the RMB into the toolkit of development finance is not just a trend—it is a necessity for a more stable and equitable global economy.